
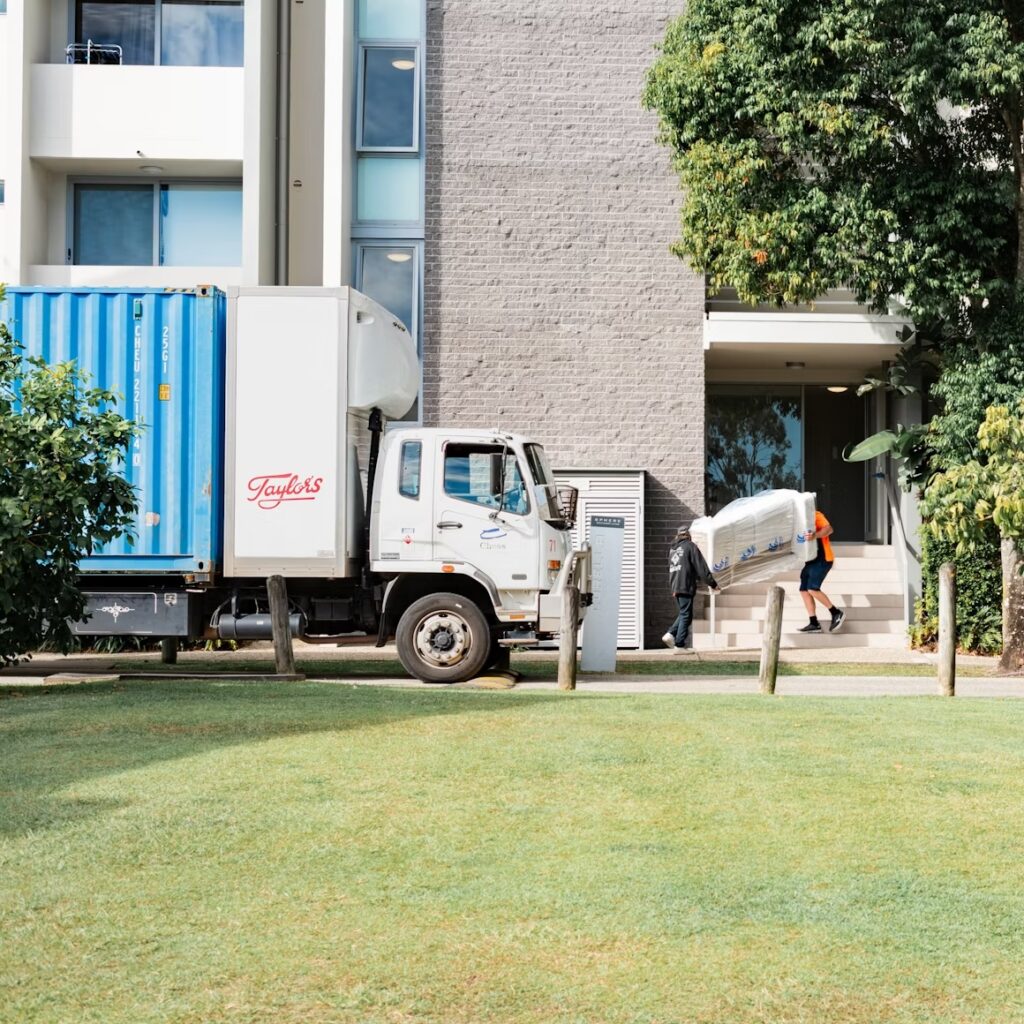
Furniture Delivery Box Truck Insurance in Arizona
Furniture delivery businesses depend on their vehicles every day. Whether you’re delivering new furniture for a retailer, providing last-mile delivery services, or operating your own delivery company, a box truck accident can affect much more than just the vehicle.
A furniture delivery operation may have exposures involving the truck, drivers, customer property, loading and unloading, and contractual insurance requirements.
For Arizona furniture delivery businesses, understanding how these coverages work together can help identify gaps before a loss occurs.
Why Furniture Delivery Businesses Have Different Insurance Needs
A box truck used for furniture delivery presents different risks than a vehicle simply traveling between jobsites.
A typical delivery operation may involve:
- Driving to multiple customer locations each day
- Transporting property belonging to others
- Loading and unloading furniture
- Entering customers’ homes or businesses
- Employing multiple drivers or delivery helpers
- Working under contracts with retailers or logistics companies
Commercial auto insurance is an important part of the insurance program, but it may not address every one of these exposures.
Commercial Auto Insurance for Furniture Delivery Trucks
Commercial auto insurance is generally designed to address risks associated with vehicles used for business.
Depending on the policy and coverage selected, a furniture delivery business may consider:
- Auto liability
- Collision
- Comprehensive
- Uninsured and underinsured motorist coverage
- Medical payments
- Other commercial auto endorsements or coverages appropriate to the operation
Liability coverage can help protect the business when an insured vehicle is responsible for bodily injury or property damage in an accident, subject to the terms of the policy.
Physical damage coverage can help protect the business’s own truck against covered losses.
For a broader explanation of these coverages, read our guide to commercial auto insurance for box trucks in Arizona.
Does Commercial Auto Insurance Cover the Furniture Being Delivered?
This is an important distinction.
Business owners should not assume that commercial auto insurance automatically insures furniture or other customer property being transported inside the truck.
A furniture delivery company may need separate coverage for property being transported, depending on the nature of its operations.
One coverage that may be relevant is motor truck cargo insurance.
Motor truck cargo coverage is generally designed to cover certain property being transported by a motor carrier, subject to the policy’s terms, limits, deductibles, and exclusions.
The appropriate coverage depends on questions such as:
- Who owns the furniture?
- Who is responsible for it while in transit?
- What does the delivery contract require?
- What types of goods are being transported?
- What is the maximum value carried at one time?
Those details should be discussed when evaluating coverage.
Loading and Unloading Creates Additional Exposure
Furniture delivery doesn’t end when the truck reaches the customer’s driveway.
Employees may have to:
- Carry furniture from the truck
- Use ramps or liftgates
- Move large items through doorways
- Navigate stairs
- Enter homes and commercial buildings
- Assemble or position furniture
That creates risks that aren’t limited to a traffic accident.
For example, a delivery worker could accidentally damage a customer’s wall or flooring while moving a couch into a home.
Another person could potentially be injured during the delivery process.
This is one reason furniture delivery businesses should evaluate their general liability exposure in addition to commercial auto insurance.
Commercial Auto vs. General Liability
Commercial auto and general liability insurance serve different purposes.
Commercial auto generally addresses covered liability arising from the use of insured vehicles.
General liability may address certain bodily injury and property damage claims arising from business operations away from the vehicle, subject to policy terms and exclusions.
A furniture delivery company may therefore need both rather than assuming one policy handles every possible claim.
The exact circumstances surrounding a loss can determine which policy or coverage may respond.
What About Damage to Customer Property?
This deserves particular attention for furniture delivery businesses.
Damage to property in your care, custody, or control can present coverage issues under standard liability policies.
For example, there is an important difference between:
- Your truck damaging another vehicle in an accident
- Furniture being damaged while transported
- An employee damaging a customer’s home during delivery
- An employee damaging the furniture being delivered
Those situations may involve different insurance coverages.
Business owners should clearly explain their operations to their insurance agent so the appropriate exposures can be evaluated.
Contract Insurance Requirements
Many furniture delivery businesses perform work for:
- Furniture retailers
- Warehouses
- Logistics companies
- Last-mile delivery companies
- Manufacturers
- Commercial customers
These companies may require specific insurance before allowing a delivery company to begin work.
Requirements can include:
- Minimum auto liability limits
- General liability insurance
- Workers’ compensation
- Cargo coverage
- Certificates of insurance
- Additional insured status
- Waivers of subrogation
- Other required endorsements
Don’t assume that simply having a commercial auto policy means you satisfy a contract.
Review the actual insurance requirements before accepting the work.
Employees and Delivery Helpers
Furniture delivery businesses should also consider who is actually operating the vehicles.
Insurance companies may ask for information about:
- Drivers
- Driving records
- Commercial driving experience
- Employee status
- Vehicle assignments
- Frequency of vehicle use
If employees assist with loading and unloading, workers’ compensation may also be an important consideration.
Arizona businesses should review applicable workers’ compensation requirements when hiring employees.
Hired and Non-Owned Vehicles
Some delivery businesses occasionally use vehicles they don’t own.
Examples might include:
- Renting an additional truck during a busy period
- Employees using personal vehicles for business errands
- Temporary replacement vehicles
Depending on the operation, hired auto and non-owned auto exposures may need to be evaluated.
Business owners should tell their agent when vehicles other than those specifically owned by the company are being used for business.
What Affects Furniture Delivery Box Truck Insurance Costs?
Insurance premiums can vary significantly between furniture delivery businesses.
Insurance companies may consider factors such as:
- Number of vehicles
- Vehicle values
- GVWR
- Driver records
- Driver experience
- Operating radius
- Annual mileage
- Garaging location
- Claims history
- Liability limits
- Physical damage coverage
- Nature of the delivery operation
A one-truck company making local deliveries may have a very different insurance profile from a multi-vehicle company operating throughout Arizona or across state lines.
For a deeper look at pricing factors, see what affects box truck insurance costs in Arizona.
New Furniture Delivery Businesses
A newly formed furniture delivery company may still be able to obtain commercial auto insurance.
However, insurance companies may ask additional questions about:
- Prior experience
- Driver history
- Expected revenue
- Planned mileage
- Operating radius
- Customers or contracts
- Vehicles
- Types and values of property being transported
Having accurate information available can make the quoting process easier.
If you’re just starting your operation, read our guide to new venture box truck insurance in Arizona.
Does GVWR Matter for Furniture Delivery Trucks?
It can.
Furniture delivery businesses commonly use larger box trucks, so owners should understand the Gross Vehicle Weight Rating of each vehicle.
GVWR can be relevant to vehicle classification, insurance underwriting, and certain commercial vehicle requirements.
Truck length alone doesn’t tell you its GVWR.
For more information, read what GVWR means for box truck insurance and commercial vehicle requirements.
Questions to Answer Before Requesting a Quote
Having the following information available can make it easier to evaluate insurance options:
- Business name and entity type
- Business address
- Years in business
- Description of operations
- Vehicle VINs
- Vehicle values
- GVWR
- Driver names and license information
- Operating radius
- Estimated annual mileage
- States traveled
- Types of furniture or property transported
- Maximum cargo value
- Current or prior insurance information
- Contract insurance requirements
For a new venture, estimates may be necessary for information that doesn’t yet have an operating history.
The important thing is to describe the intended operation accurately.
Common Furniture Delivery Insurance Mistakes
Some potential mistakes include:
- Assuming commercial auto automatically covers cargo
- Buying insurance before reviewing customer contracts
- Failing to disclose the actual delivery operation
- Using drivers who haven’t been disclosed to the insurer
- Overlooking loading and unloading exposures
- Selecting coverage based only on price
- Failing to update insurance as vehicles or operations change
A policy should reflect what the business actually does.
Final Thoughts
Furniture delivery businesses face more than just the risk of an auto accident.
Vehicles, drivers, cargo, loading and unloading, customer property, employees, and contractual requirements can all create different exposures.
Commercial auto insurance is an important foundation, but furniture delivery companies should evaluate the entire operation rather than assuming one policy covers every risk.
Understanding these exposures before signing a delivery contract or putting a truck on the road can help Arizona businesses make better insurance decisions.
Need Furniture Delivery Box Truck Insurance in Arizona?
Shawn Orr Insurance helps Arizona businesses evaluate insurance for:
- Furniture delivery box trucks
- Last-mile delivery operations
- New ventures
- Commercial delivery vehicles
- Multi-vehicle fleets
We can help review your vehicles, drivers, operations, and contractual insurance requirements to identify commercial insurance options for your business.
Contact us today to discuss insurance for your Arizona furniture delivery operation.

