
Does Commercial Auto Insurance Cover Tools in Your Work Truck?
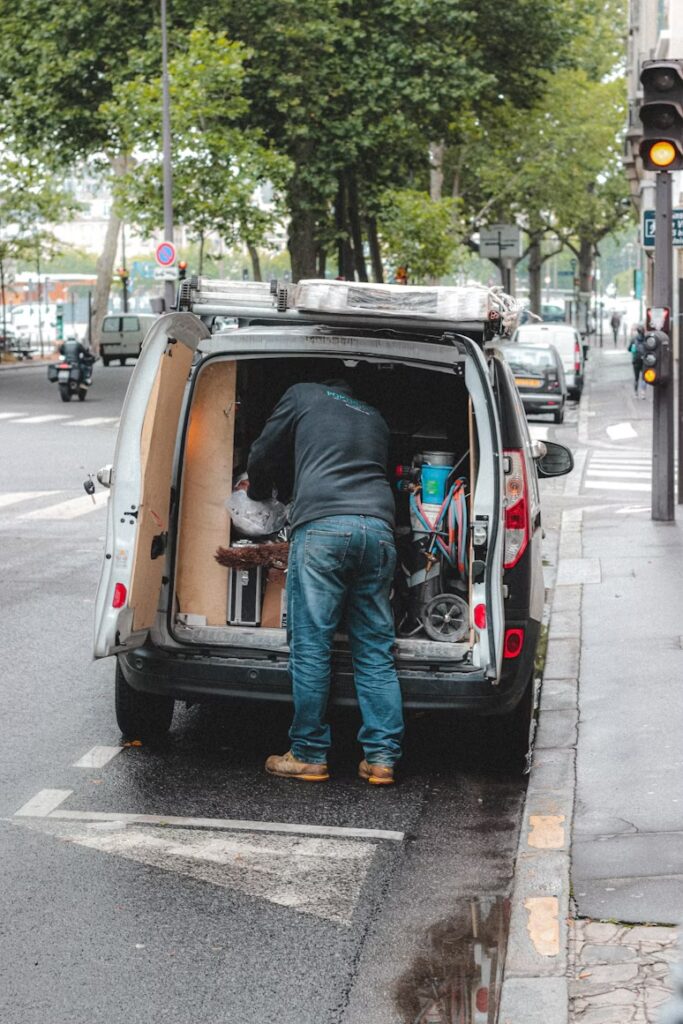
If your work truck or service van is insured under a commercial auto policy, you might assume the tools and equipment inside the vehicle are insured too.
That isn’t necessarily the case.
Imagine an Arizona HVAC contractor has a service van stolen overnight. The van contains $12,000 worth of power tools, diagnostic equipment, and other HVAC equipment.
The contractor carries comprehensive coverage on the van.
Will the commercial auto policy pay for the $12,000 of equipment that was inside?
Not necessarily.
Commercial auto insurance and coverage for tools and equipment generally address different exposures. Contractors who regularly carry expensive equipment should understand that distinction before a theft or other loss occurs.
Does Commercial Auto Insurance Cover Tools?
Contractors should not assume that a standard commercial auto policy automatically covers tools and equipment carried inside an insured vehicle.
Commercial auto insurance is primarily designed to address risks associated with the vehicle itself and liability arising from its use.
Depending on the coverage selected, a commercial auto policy may include:
- Auto liability
- Collision
- Comprehensive
- Uninsured and underinsured motorist coverage
- Medical payments
- Other applicable commercial auto coverages or endorsements
Tools, equipment, and other business property carried inside the vehicle can represent a separate exposure.
The exact coverage available depends on the policy, endorsements, circumstances of the loss, and property involved.
What Happens If Someone Steals Tools From Your Work Truck?
Consider an electrician who parks a service van at home overnight.
Someone breaks into the van and steals:
- Power tools
- Testing equipment
- Hand tools
- Cable-pulling equipment
- Specialty electrical tools
The contractor may have comprehensive coverage protecting the van against certain theft-related losses.
But that does not necessarily mean the commercial auto policy covers all of the business property stolen from inside it.
This distinction can become expensive quickly.
A contractor who accumulates tools over many years may have substantially more money invested in equipment than they realize.
What Insurance Can Cover Contractor Tools and Equipment?
Contractors may use inland marine insurance, tools and equipment coverage, or another form of business property coverage designed for movable property.
Unlike property that remains at one fixed business location, contractor equipment frequently moves between:
- Work trucks
- Service vans
- Jobsites
- Customer locations
- Storage locations
- The contractor’s shop
That mobility is one reason contractors should specifically evaluate how their tools are insured.
Depending on the policy, coverage may be available for certain tools and equipment while they’re being transported or temporarily located away from the contractor’s primary business location.
Coverage terms, limits, deductibles, exclusions, and valuation provisions can vary considerably between policies.
Commercial Auto vs. Tools and Equipment Insurance
It helps to think about the two exposures separately.
| Exposure | Coverage to Evaluate |
|---|---|
| Damage to your work truck in a covered collision | Commercial auto physical damage |
| Theft of the insured vehicle | Commercial auto comprehensive, if selected and applicable |
| Liability after causing an auto accident | Commercial auto liability |
| Contractor tools stolen from the vehicle | Tools/equipment or inland marine coverage may apply |
| Equipment damaged away from your shop | Tools/equipment or inland marine coverage may apply |
| Business property transported between jobsites | Property/inland marine coverage should be evaluated |
Carry expensive tools in your work vehicle?
Shawn Orr Insurance helps Arizona contractors evaluate commercial auto and tools & equipment coverage. Request a quote →
The exact policy language controls whether a particular loss is covered.
The important takeaway is simple:
Insuring the truck does not automatically mean you’ve insured everything inside the truck.
What Types of Contractors Should Consider Tools and Equipment Coverage?
This issue can affect almost any trade that carries equipment between jobsites.
Examples include:
- Plumbers
- HVAC contractors
- Electricians
- General contractors
- Landscapers
- Painters
- Carpenters
- Flooring contractors
- Handymen
- Restoration contractors
An Arizona plumber may carry drain-cleaning equipment and power tools.
An HVAC technician may carry diagnostic equipment, recovery equipment, gauges, and specialty tools.
An electrician may carry meters, testers, drills, conduit tools, and other equipment.
The specific trade matters less than the underlying question:
How much business property would you have to replace if everything in your work vehicle disappeared tonight?
How Much Are the Tools in Your Work Truck Worth?
Many contractors underestimate this number.
Instead of guessing, create an inventory of the equipment you regularly carry.
Include items such as:
- Power tools
- Hand tools
- Diagnostic equipment
- Specialty trade equipment
- Ladders
- Compressors
- Generators
- Testing equipment
- Other portable equipment
Then estimate what it would cost to replace those items.
A few hundred dollars here and a few thousand dollars there can quickly become a significant business exposure.
Photographs, receipts, serial numbers, and an equipment inventory can also be useful records to maintain.
What About Tools Owned by Employees?
This deserves separate attention.
Contractors shouldn’t automatically assume that tools personally owned by employees receive the same treatment as equipment owned by the business.
If employees bring their own tools to jobsites, ask how—or whether—those tools are covered under the business’s insurance program.
Policy terms can differ regarding property ownership, covered property, limits, and exclusions.
This is something worth addressing before an employee’s tools are stolen rather than after a claim occurs.
What About Materials and Supplies in the Truck?
Tools aren’t the only property contractors carry.
A plumber might transport fixtures and plumbing materials.
An electrician might carry wire, conduit, breakers, and electrical components.
An HVAC contractor might transport replacement parts or equipment awaiting installation.
Materials, inventory, customer property, and contractor-owned tools may not necessarily be treated identically by an insurance policy.
If your vehicles regularly transport valuable property, explain exactly what you carry and who owns it when discussing insurance.
Are Tools Covered at a Jobsite?
One advantage of specifically evaluating inland marine or tools and equipment coverage is that contractors don’t keep their equipment in one place.
Tools may move from the vehicle to a jobsite and remain there temporarily.
However, contractors shouldn’t assume that every policy covers equipment everywhere and under every circumstance.
Important questions can include:
- Where is the equipment covered?
- Is theft from an unattended vehicle covered?
- Are there theft limitations?
- Is equipment covered overnight at a jobsite?
- Are there per-item limits?
- What deductible applies?
- How is damaged or stolen equipment valued?
- Are certain types of equipment excluded?
Those details can be just as important as the overall coverage limit.
What If the Entire Work Truck Is Stolen With the Tools Inside?
This scenario demonstrates why the distinction matters.
Suppose an Arizona plumbing contractor has a cargo van worth $35,000 containing $20,000 of tools and equipment.
The entire van is stolen.
Potentially, you’re dealing with two different categories of property:
The van
Commercial auto physical damage coverage may respond to a covered theft if the appropriate coverage was purchased.
The tools and equipment
Separate tools/equipment or inland marine coverage may need to respond to covered business property inside the vehicle.
Whether either policy pays—and how much—depends on the actual policy terms and facts surrounding the loss.
A contractor shouldn’t wait until a $55,000 combined loss to discover how those coverages interact.
Does General Liability Insurance Cover Stolen Tools?
Contractors also sometimes confuse general liability insurance with property coverage.
General liability is primarily designed to address certain claims alleging bodily injury, property damage, and other covered liability exposures involving third parties.
It should not generally be viewed as a replacement for coverage protecting the contractor’s own tools and equipment.
Commercial auto, general liability, and inland marine/tools coverage serve different purposes within a contractor’s insurance program.
Insurance for Tools Carried by Arizona Contractors
Arizona contractors frequently operate from their vehicles.
A service van or work truck may effectively function as a mobile workshop, carrying the equipment necessary to complete several jobs throughout the day.
That makes it important to evaluate the vehicle and its contents separately.
If you use a truck, van, or other vehicle for your contracting business, our guide to commercial auto insurance for contractors in Arizona explains additional vehicle exposures involving drivers, employees, trailers, and business use.
Plumbing contractors can also read our guide to plumbing tools and equipment insurance in Mesa, Arizona for a trade-specific look at protecting equipment that travels between jobsites.
Questions to Ask About Your Tools and Equipment Coverage
Before assuming you’re protected, consider asking:
- Are tools covered while they’re inside my work vehicle?
- Is theft from a locked vehicle covered?
- Are tools covered overnight?
- What happens when equipment is left at a jobsite?
- Are employee-owned tools covered?
- Is there a maximum limit for any one item?
- What deductible applies?
- Is replacement cost available, or is depreciation considered?
- Does the policy cover newly purchased equipment?
- Are trailers and equipment inside trailers treated differently?
The answers depend on the actual insurance policy.
Common Insurance Mistakes Contractors Make With Tools
Some potential mistakes include:
- Assuming commercial auto covers everything inside the vehicle
- Never calculating the total value of tools carried
- Buying a coverage limit that hasn’t kept pace with new equipment purchases
- Assuming employee-owned tools are covered
- Ignoring policy limitations on theft
- Failing to maintain an equipment inventory
- Assuming materials and tools are treated identically
- Choosing coverage based only on premium
The right insurance program should reflect what the contractor actually owns, carries, and uses.
What Information Helps When Getting a Quote?
If you’re looking for tools and equipment coverage, it can help to know:
- Your type of contracting business
- Approximate total equipment value
- Value of your most expensive individual items
- Where equipment is normally stored
- Whether equipment stays in vehicles overnight
- Whether equipment is left at jobsites
- Whether employees own any of the tools
- Whether you use enclosed or open trailers
- Your prior loss history
An insurance company may request additional information depending on the type and value of equipment.
The Bottom Line
Don’t assume your commercial auto policy covers the tools inside your work truck.
Commercial auto insurance can protect important vehicle-related exposures, but contractor tools and equipment may require separate coverage.
For Arizona contractors whose vehicles function as mobile workshops, that distinction can represent thousands—or tens of thousands—of dollars of uninsured property if it isn’t addressed properly.
Inventory your equipment, understand where it’s stored, and review how your policies would respond before a loss occurs.
Need Commercial Auto and Tools & Equipment Insurance in Arizona?
Shawn Orr Insurance helps Arizona contractors evaluate coverage for both their commercial vehicles and the tools and equipment they rely on to operate their businesses.
We work with:
- Plumbers
- HVAC contractors
- Electricians
- General contractors
- Other Arizona trade businesses
If you have a work truck or service van carrying valuable equipment, we can help you review your commercial auto and tools and equipment insurance options.
Contact Shawn Orr Insurance today to request an Arizona contractor insurance quote.

